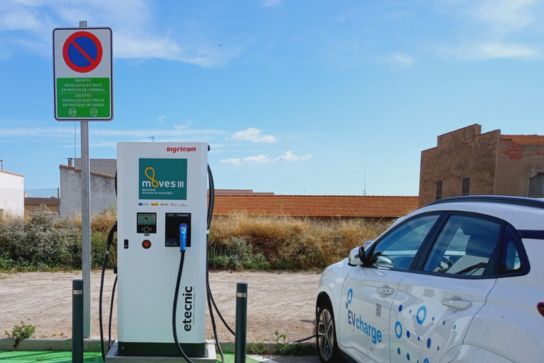
The end date for the MOVES III Plan is extended until July 31, 2024
Discover how the MOVES III Plan, a cornerstone of the ambitious Recovery, Transformation and Resilience Plan, is paving the way toward the decarbonization of electric mobility in our country. This subsidy program not only drives the adoption of electric vehicles but also facilitates the installation of charging points, setting the stage to achieve the ambitious PNIEC 2021-2030 targets: 5.5 million electric vehicles on our roads by 2030!
“Demand has exceeded our expectations, with over 250,000 applications registered, and we still have an astounding €290 million fund available to continue supporting your projects,” state sources from Miteco.
And here is the exciting news! Driven by strong interest and response, the Council of Ministers, supported by the Ministry for the Ecological Transition and the Demographic Challenge (Miteco), has given the green light to Royal Decree 821/2023. The decree extends the window of opportunity for the MOVES III Program by seven additional months, until July 31, 2024, providing more time to leverage this opportunity to electrify the mobility of businesses, legal entities, and public administrations.
Don’t let this opportunity pass you by! Join the electric mobility revolution with Etecnic and make the most of the boost provided by the MOVES III Plan.
Together, we can take your project to the next level.
The approved Royal Decree introduces changes to the regulatory framework of the MOVES III program
The modifications introduced to the MOVES III plan subsidies published by IDAE highlight:
- Changes in Aid Levels (% of Eligible Cost):
- Until 12/31/2023: Subsidies vary depending on the applicant type and installation location. For example, for individuals, self-employed workers, and homeowners’ associations, the subsidy is generally 70%, increasing to 80% in municipalities with fewer than 5,000 inhabitants.
- From 01/01/2024: New subsidy amounts are introduced, aligning with the thresholds of the new GBER (General Block Exemption Regulation). These subsidies distinguish to a greater extent between applicant types and locations, with percentages ranging between 20% and 80%.
- Subsidy Limits:
- For individuals, the limit is €5,000 per application.
- For self-employed workers and SMEs applying under the de minimis Regulation, the limit is €200,000 accumulated over three years, or €100,000 for self-employed individuals in road freight transport.
- For corporations, public administrations, and homeowners’ associations, the cap is €800,000 per application, with a maximum of €25 million per call.
- Eligible Costs:
- Eligible expenses include project design, civil works, engineering, charging infrastructure, grid connection, land preparation, and permitting fees.
- Costs related to renewable energy generation, local energy storage, integrated payment systems, signage, management systems, control, and security are also considered eligible.
- Application Procedure:
- Applications must be submitted through the portal of the corresponding autonomous community. On this point, companies and city councils have contracted Etecnic to manage the application process, administration, and subsequent justification.
- Installation Execution:
- Individuals, self-employed workers, homeowners’ associations, and public administrations without commercial activity may carry out the installation from April 10.
- Companies and public entities with commercial activity must wait for their respective autonomous community to open the call before applying for aid.
- Required Application Documentation:
- Individuals and self-employed workers must provide a copy of their DNI/NIE, proof of registration in the Business Register, tax compliance certificates, etc.
- Companies and homeowners’ associations need to present a copy of their NIF, power of attorney documentation, and declarations regarding company status and previous subsidies received. If your business needs support with this process, Etecnic can assist you throughout the journey.
- Investment Justification:
- Applicants must submit technical reports or installation projects corresponding to the installed capacity, along with itemized invoices, proof of payment, and Electrical Installation Certificates (CIE).
These modifications affect companies, legal entities, and public administrations carrying out economic and/or commercial activity, which have a six-month period to adapt to the new provisions—meaning all required adjustments must be completed before December 31, 2023.
Once the subsidy has been granted, the beneficiary has 12 months to complete and finalize legal compliance for the charging infrastructure.
If you are considering taking the leap into electric mobility, don’t run out of time—get prepared with a specialist like Etecnic!

New infrastructure must support smart charging capabilities
Regarding the installation of charging points and the deployment of new infrastructure providing power transfer equal to or less than 22 kW, these must be capable of supporting smart charging capabilities.
Smart charging refers to optimizing the recharging process, where energy delivered to the electric vehicle is dynamically adjusted in real time or scheduled. This is achieved using an OCPP-compliant management and control platform, such as EVcharge.
Additionally, the RDL amendment requires that the nominal capacity of on-site electricity generation must not exceed the nominal power or maximum refueling capacity of the connected charging infrastructure. According to ministry estimates, these modifications “affect fewer than 2% of total applications.”
Is the tax deduction up to a maximum of 15% compatible?
In June 2023, a tax deduction of up to a maximum of 15% on personal income tax (IRPF) returns was approved for investments in electric vehicles or charging points, which is compatible with the MOVES III program.
- Deduction for the Purchase of Electric Vehicles: If you purchase an electric vehicle, you can deduct 15% of the acquisition value on your personal income tax (IRPF) return. The deduction must be claimed in the tax period during which the vehicle was registered.
- Deduction for the Installation of Electric Vehicle Battery Charging Systems: Taxpayers can deduct 15% of the amounts paid for installing EV battery charging systems in a property they own. This deduction is applicable provided the installation is not tied to an economic/commercial activity.
Deductions will apply as long as the EV purchase or charging system installation occurs between June 30, 2023, and December 31, 2024.
Etecnic: Experts in assisting companies and public entities
Throughout the duration of the MOVES III Plan, Etecnic has helped more than 70 companies to date in processing their subsidies. This service includes preparing technical documentation, offering step-by-step application guidance, and managing project paperwork. Our collaboration also covers ongoing support during the charging project justification phase.
PGRpdiBpZD0iemZfZGl2X0hDanFKRmhtRTIxNERka3FoMlNCZzkwampkbnZFRkNvRENaYmdwTVh0VjgiPjwvZGl2PjxzY3JpcHQgdHlwZT0idGV4dC9qYXZhc2NyaXB0Ij4oZnVuY3Rpb24oKSB7CnRyeXsKdmFyIGYgPSBkb2N1bWVudC5jcmVhdGVFbGVtZW50KCJpZnJhbWUiKTsgIApmLnNyYyA9ICdodHRwczovL2Zvcm1zLnpvaG9wdWJsaWMuY29tL21hcmtldGluZzM1MS9mb3JtL0VURUNOSUNNT1ZFUy9mb3JtcGVybWEvSENqcUpGaG1FMjE0RGRrcWgyU0JnOTBqamRudkVGQ29EQ1piZ3BNWHRWOD96Zl_yc3pmbT0xJzsKZi5zdHlsZS5ib3JkZXI9Im5vbmUiOyAgICAgICAgICAgICAgICAgICAgICAgICAgICAgICAgICAgICAgICAgICAKZi5zdHlsZS5oZWlnaHQ9IjcwMHB4IjsKZi5zdHlsZS53aWR0aD0iMTAwJSI7CmYuc3R5bGUudHJhbnNpdGlvbj0iYWxsIDAuNXMgZWFzZSI7Ly8gTm8gSTE4Tgp2YXIgZCA9IGRvY3VtZW50LmdldEVsZW1lbnRCeUlkKCJ6Zl9kaXZfSENqcUpGaG1FMjE0RGRrcWgyU0JnOTBqamRudkVGQ29EQ1piZ3BNWHRWOCIpOwpkLmFwcGVuZENoaWxkKGYpOwp3aW5kb3cuYWRkRXZlbnRMaXN0ZW5lcignbWVzc2FnZScsIGZ1bmN0aW9uICgpewp2YXIgemZfaWZybV9kYXRhID0gZXZlbnQuZGF0YS5zcGxpdCgifCIpOwp2YXIgemZfcGVybWEgPSB6Zl9pZnJtX2RhdGFbMF07CnZhciB6Zl_pZnJtX2h0X253ID0gKCBwYXJzZUludCh6Zl_pZnJtX2RhdGFbMV0sIDEwKSArIDE1ICkgKyAicHgiOwp2YXIgaWZyYW1lID0gZG9jdW1lbnQuZ2V0RWxlbWVudEJ5SWQoInpmX2Rpdl_IQ2pxSkZobUUyMTREZGtxaDJTQmc5MGpqZG52RUZDb0RDWmJncE1YdFY4IikuZ2V0RWxlbWVudHNCeVRhZ05hbWUoImlmcmFtZSIpWzBdOwppZiAoIChpZnJhbWUuc3JjKS5pbmRleE9mKCdmb3JtcGVybWEnKSA+IDAgJiYgKGlmcmFtZS5zcmMpLmluZGV4T2YoemZfcGVybWEpID4gMCApIHsKdmFyIHByZXZJZnJhbWVIZWlnaHQgPSBpZnJhbWUuc3R5bGUuaGVpZ2h0OwppZiAoIHByZXZJZnJhbWVIZWlnaHQgIT0gemZfaWZybV9odF_udyApIHsKaWZyYW1lLnN0eWxlLmhlaWdodCA9IHpmX2lmcm1faHR_bnc7Cn0gICAKfQp9LCBmYWxzZSk7Cn1jYXRjaChlKXt9Cn0pKCk7PC9zY3JpcHQ+